kingson on May 13, 2021 No Comments
[ad_1]
“Only when individuals are clear on the purpose of the purchase, they should decide on the avenue. For example, if someone is buying for investments, including for tactical bets, a gold ETF is a better option. If it’s for a future event like a daughter’s wedding, a person can look at digital gold or sovereign gold bonds,” said Basavaraj Tonagatti, a Bengaluru-based Sebi-registered investment adviser.
Investment advisers usually suggest allocating 5-15% to gold in the investment portfolio as it is a hedge against currency volatility and inflation.
“While we believe investors should have some gold in the portfolio, we are not very bullish on it in the near term,” said Jeevan Kumar, head of investment advisory, Geojit Financial Services.

View Full Image
Motilal Oswal Financial Services expects prices to reach ₹50,000 per 10 gm in the near term and ₹56,500 per 10 gm or more over the next 12-15 months.
According to India Bullion and Jewellers Association, gold prices are at ₹47,764 per 10 gm, excluding taxes.
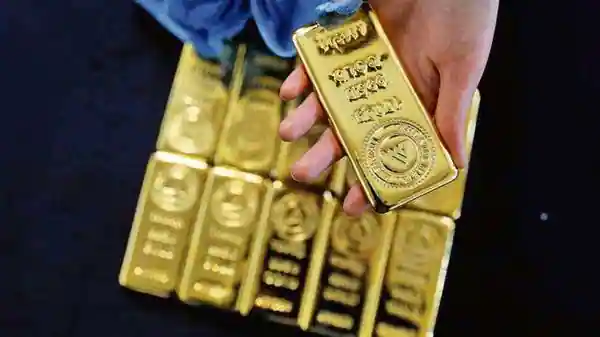
PHYSICAL GOLD
Jewellers have started offering video conference service to clients. You can book an appointment and check whatever you want to buy in real time. The jeweller will send you the link for payment and deliver the gold to your place.
“On average, a client spends about an hour-and-a-half, and the conversion rates on video conference is 85%. Before the appointment, we check with clients of their preference and accordingly display our collection,” said Vinod Hayagriv, managing director, C. Krishniah Chetty Group of Jewellers.
Pros: You can feel and touch it. The owner can pledge it for a quick loan.
Cons: There could be a storage cost if you keep it in a bank locker. Jewellers add making charges.
SOVEREIGN GOLD BONDS
A better substitute to holding the yellow metal in physical form, the RBI issues sovereign gold bonds (SGBs) in denominations of 1 gm of gold and multiples thereof. These bonds also offer an annual interest rate of 2.5% on the initial investment amount.
“They are good for those looking at accumulating gold and for investors, depending on the horizon. But ETFs have better liquidity,” said Tonagatti.
The new tranche of SGB will open for subscription on 17 May and close on 21 May. The bonds mature after eight years, and early redemption is allowed after five years. The only problem is that these are not on tap—the government issues SGBs in tranches. For example, there is no issue of SGB on Akshaya Tritiya.
An investor can buy them on stock exchanges. “But it is not easy to get SGB at the right price in the secondary market. Sellers typically ask for a premium to the prevailing gold prices,” said Vikram Dalal, managing director, Synergee Capital Services.
Pros: An investor earns 2.5% interest every year. Investors get the prevailing gold prices at the time of redemption. There is no storage cost. Can be pledged for loans.
Cons: Secondary market lacks liquidity and investors could make a loss when selling on exchanges.
DIGITAL GOLD
To make physical gold more attractive, investment apps and wallets are offering digital gold. An individual can buy gold for as low as ₹1 at any time of the day. Like in physical gold, the buyer must pay 3% goods and services tax (GST).
Buyers can ask for delivery of physical gold once they have accumulated at least 1 gm of the precious metal. Alternatively, they can also sell it on the wallet or investment apps.
However, there is a significant difference in the buying and selling price due to GST.
Pros: There are no storage charges. The option works for those seeking to buy physical gold at a later date by saving small amounts.
Cons: This area is not as well-regulated as SGBs or gold ETFs. You are forced to go through the same app or platform to either sell or take delivery. If you take physical delivery of gold, there will be making charges.
EXCHANGE-TRADED FUNDS
Gold ETFs are primarily paper gold. The money you invest will be pegged to 24-carat gold. The underlying asset is gold and some cash. To invest in these ETFs, you need to open a demat account.
When you redeem, you will get the monetary equivalent of the price of gold on the day of redemption. ETFs have two costs: expense ratio and the cost of opening a demat account.
“Mutual funds get an offset on the GST, which means at any sale of physical gold, they get an offset benefit from the GST paid at the time of buying. Effectively, this does not lead to any loss to investors on account of the GST levy. Unlike physical gold, gold ETFs straight away save them a 3% cost,” said Chirag Mehta, senior fund manager – alternative investments, Quantum Asset Management Company.
Pros: There’s no storage cost and they score over others when it comes to liquidity.
Cons: Expense ratio and demat account maintenance charges.
You can also invest in gold through gold savings funds. They are similar to gold ETFs except for the fact that they do not trade on stock exchanges. Instead, you can purchase and sell the units of the gold savings fund at the prevailing net asset value (NAV) on any business day.
When buying gold on this Akshaya Tritiya, choose the instrument based on whether you want to invest or accumulate gold for the future and the money you want to spend.
Never miss a story! Stay connected and informed with Mint.
Download
our App Now!!
[ad_2]
Source link
leave your comment
Advertisement






